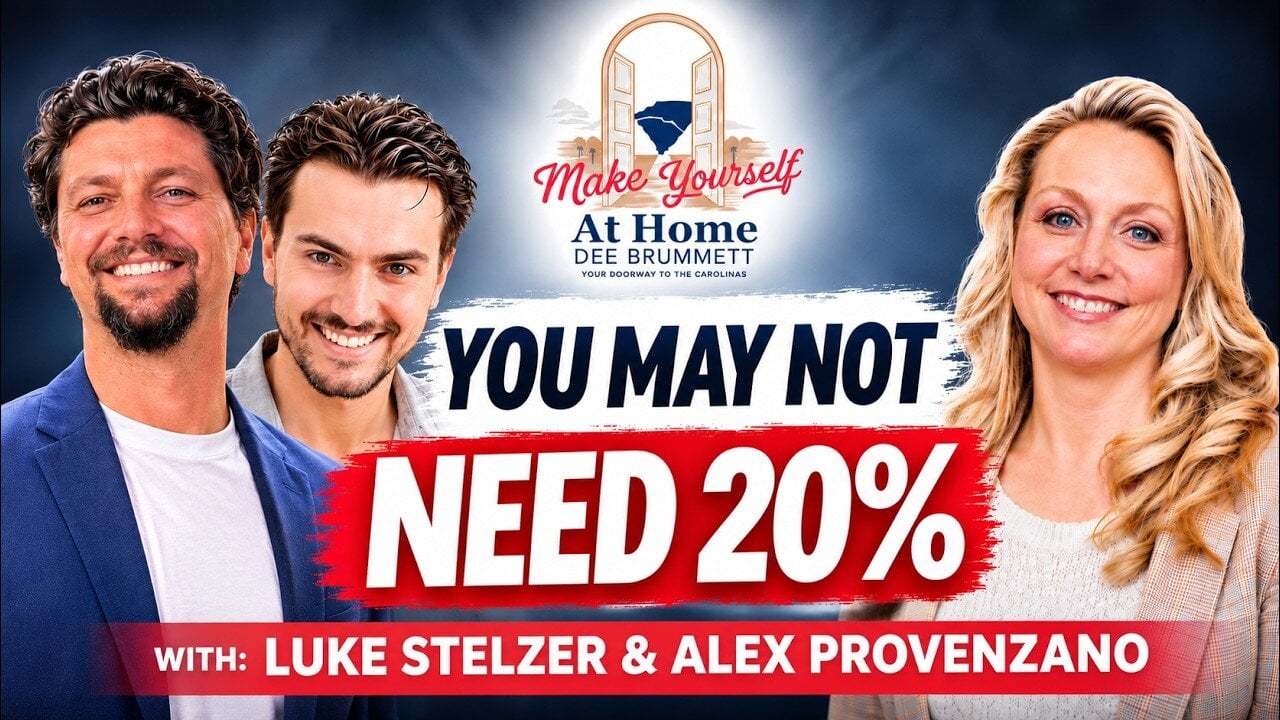
Does buying a home in Charlotte really require perfect credit, 20% down, and two years at the same job? In Part 1 of Make Yourself at Home, I sat down with Luke Stelzer of MTG Home Loans, the company's president, and loan officer Alex Provenzano. They explained what lenders look for, which documents they ask for, and which myths keep buyers waiting.
Quick takeaway: Ask a lender before you count yourself out. The guests say the answers are often better than buyers expect.
Meet Luke Stelzer and Alex Provenzano
Luke is the president of MTG Home Loans in Charlotte, a certified mortgage banker and accredited mortgage professional. He oversees operations and lending strategy across purchase, refinance, FHA, VA, USDA, jumbo, and investor loans. He says he loves working with people at every stage and finding small ways to improve the process for the customer.
Alex has more than five years of mortgage experience. He started in 2020, which he calls probably the worst time to begin. The market needed bodies for applications, and he had to learn the rest on the job. Then rates climbed from about three to seven percent and volume dropped. He says adapting and being stubborn kept him in the business.
What Happens After You Apply: The Four Cs
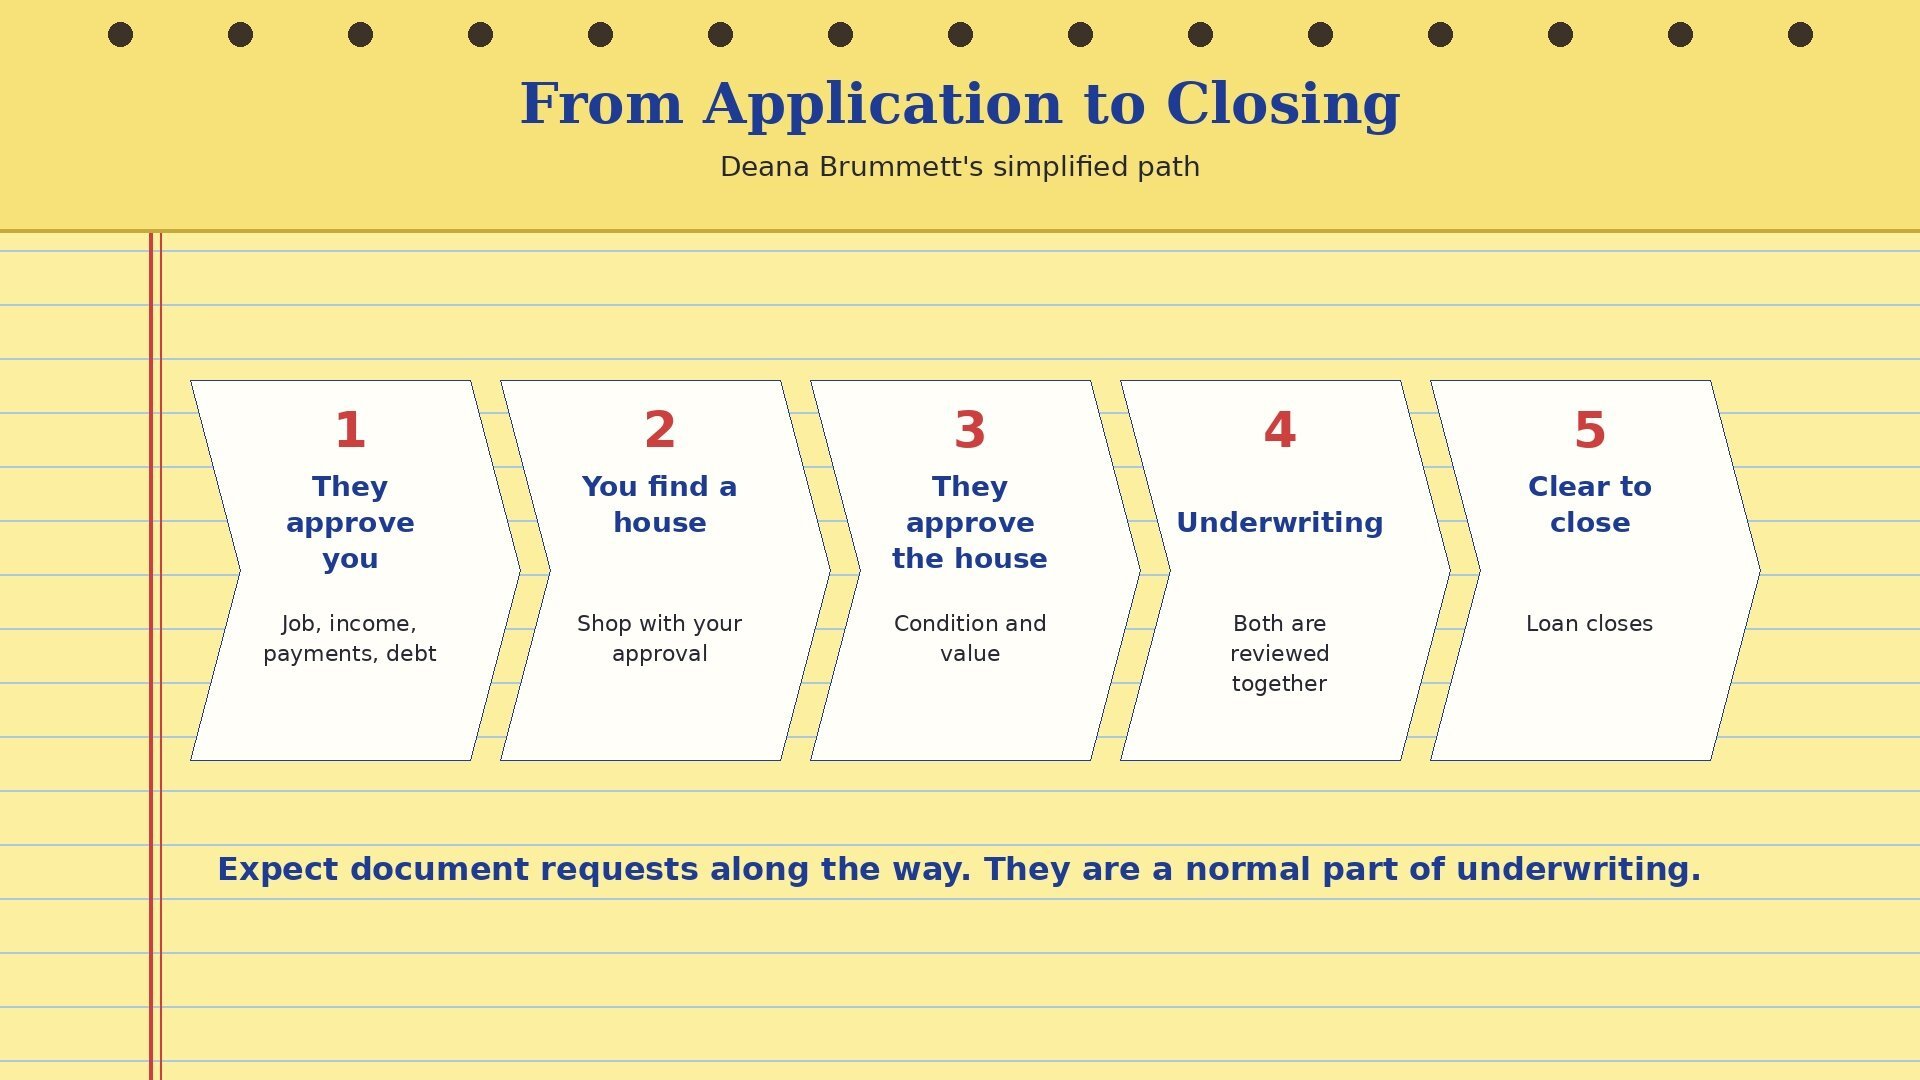
I explain the process to first-time buyers in simple steps. The lender approves you, you find a house, the lender approves the house, and then underwriting reviews both. I asked what happens behind the scenes.
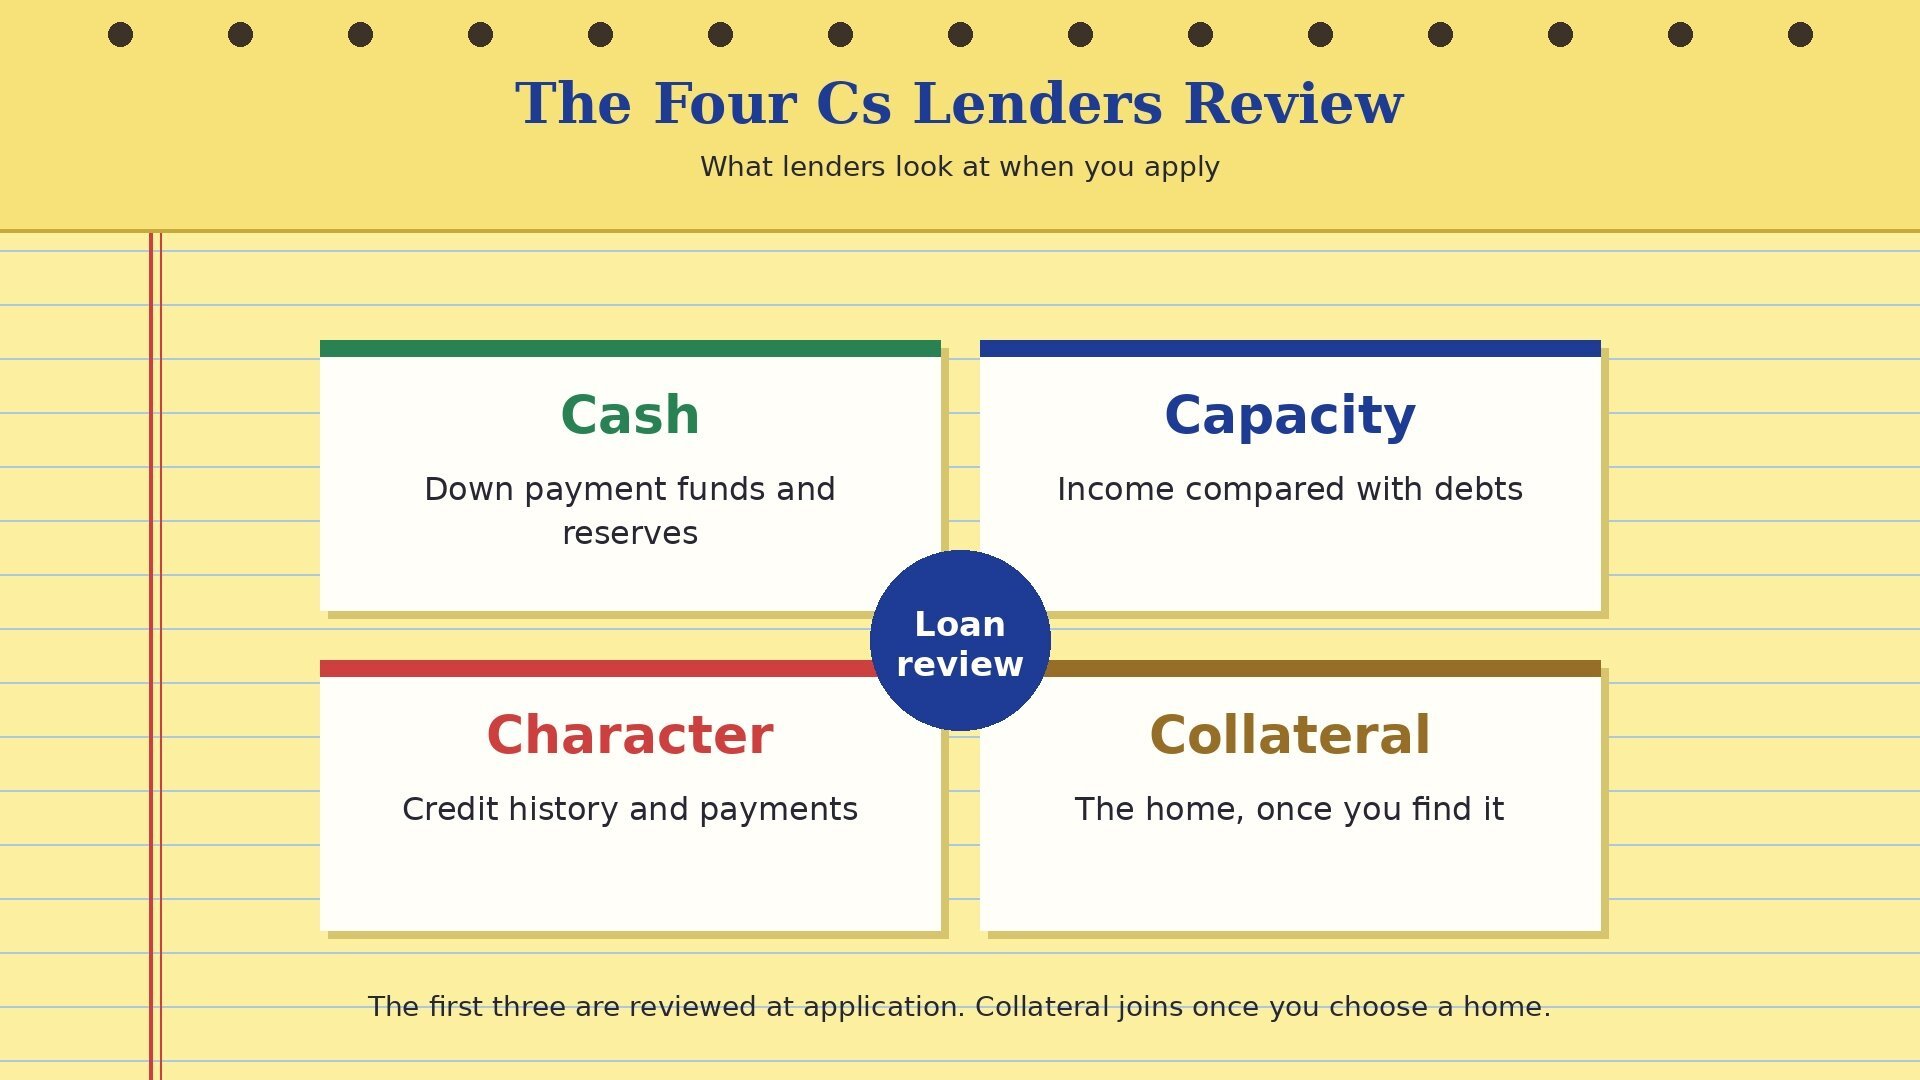
Luke says the review comes down to four Cs:
Cash: how much you can put down, and any reserves.
Capacity: your income compared with your debts, and room for a new payment.
Character: your credit report and payment history.
Collateral: the home itself, which is added once you find one.
At application, Luke Stelzer and Alex Provenzano of MTG Home Loans review the first three. The guidelines are strict and documented, so the lender checks whether you can repay.
Why Lenders Ask for So Many Documents
I tell every buyer there will be a day they feel like the lender has asked for the same piece of paper 14 times. MTG Home Loans president Luke Stelzer and Alex explained why. Every item needs backup, and each loan product has guidelines that spell out what is needed. A computer underwriter generates the list, and the human underwriter verifies it.
It differs for each borrower. If you are not self-employed, you may not need tax returns. One of them put it this way: a conventional loan is for a conventional file, while an FHA loan with down payment assistance needs more. The guests say bank statements are the hardest item to get right.
“When we ask for a bank statement, we really just want a PDF for the month or two. For some reason it becomes one of the most impossible tasks, because you'll end up getting a picture of the computer screen or they'll print it out and they'll take a picture of half of it, crinkled up and blurry. [...] You need your name, a partial of the account, and every single page.”
A simple mortgage document checklist from the episode:
Send the original PDF, not a photo of your screen.
Include every page, with your name and part of the account number.
Expect a transaction history in some cases.
Be ready to explain large deposits.
They explained that large deposits need sourcing because of rules like the Patriot Act, and complex commission pay stubs need extra review. Guidelines also change often.
Mortgage Myths: You Need Perfect Credit
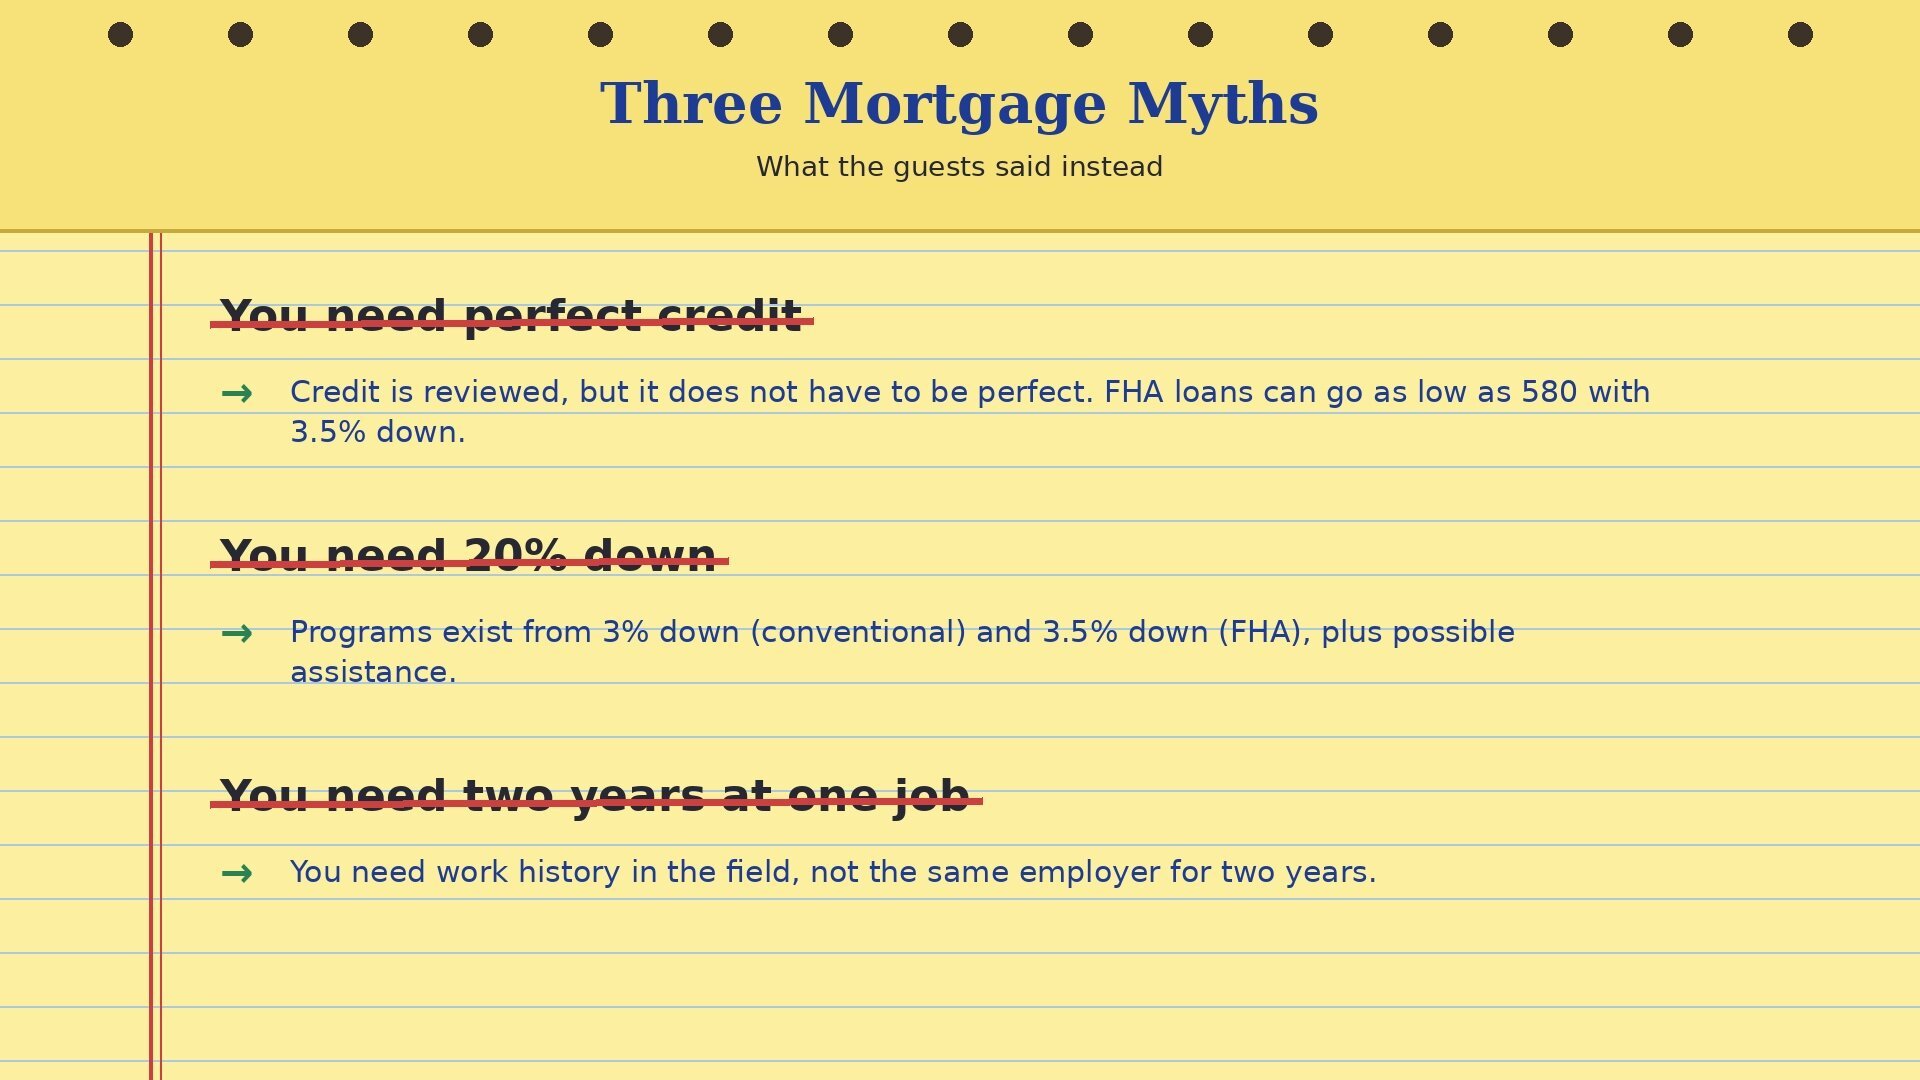
Credit will be reviewed, the guests say, with a hard pull before closing. But it does not have to be perfect.
“We're ultimately on the borrower's side. Anything we ask you for, anything we're reviewing, we're trying to find a strategy to help you get the best structure and to get this loan closed. We're on your side. There's very little, honestly, human judgment that goes into approving a loan nowadays.”
They said approvals often start in the low 600s, with about 620 ideal. An FHA loan can go as low as 580 with 3.5 percent down, and they have closed loans at that level. Alex adds that he has never seen a credit score drop 20 points from a pull for a home. These are their experiences, so ask your own lender what applies to you.
Mortgage Myths: You Need 20 Percent Down
One guest says this myth still comes up monthly, even from people who have bought before. Programs exist with as little as 3 percent down on eligible conventional loans and 3.5 percent on FHA loans. Down payment assistance may help beyond that.
Mortgage Myths: You Need Two Years at the Same Job
You do need work history, the guests say, but not at the same employer. A new job can qualify if the employer verifies your start date and the income is likely to continue. Lenders look at whether you have worked in the same field and whether the income looks stable.
Build Your Home-Buying Team and Ease the Anxiety
I tell my buyers they are building a team, and they are the boss. You want an agent and a lender who communicate. Many people fear a decline, like a card being declined at the store. My stepdad's advice was that you are simply renting a lender's money, and there is no judgment in the answer.
Alex starts with the fears. He asks what you think your credit is, and says buyers often put barriers in front of themselves. Sometimes, he says, it is easier to save for a down payment than to spend thousands paying off collections. Talk to a lender first.
The guests say they use automation, but people explain it.
“You can't just rely on an automation to give the updates and to ask for the documents and there's no explanation and no anticipation. We want to be proactive and we want to anticipate what's next, and part of that is anticipating your anxiety. And we've been through this enough times and we know when you get a list of conditions, it's normal. [...] We can't let a piece of software tell you these are the conditions and let you spiral down a rabbit hole.”
You Are Not Behind
I told the guests that the average age of a first-time buyer rose from about 28 to 38 between 2020 and 2025. You are not behind and not ahead. Nobody is in this race but you. This is general information, not financial advice, so confirm details with your lender.
Frequently Asked Questions About Mortgages in Charlotte
What do mortgage lenders look at when reviewing an application?
Four Cs: cash, capacity, collateral, and character.
Do I need perfect credit to buy a house?
No. The guests say imperfect credit does not automatically stop approval. The loan program and the overall application matter.
Do I have to put 20% down?
No. The episode mentions eligible conventional loans with as little as 3% down and FHA loans with as little as 3.5% down.
Do I need two years at the same job?
Not necessarily. Work history in the same field matters, and a new job may qualify.
Connect With Luke Stelzer, Alex Provenzano, and Deana Brummett
VisitMTG Home Loans or find them onFacebook andLinkedIn. To follow my work, visitAt Home in the Carolinas or find me onLinkedIn,Instagram, andFacebook. Thank you to Luke Stelzer of MTG Home Loans and Alex for making mortgages less scary. We will continue this conversation in another episode.
Apply to Be a Guest on the Make Yourself at Home Podcast
Charlotte and the Carolinas are full of professionals helping buyers feel at home. If you work in lending, real estate, construction, or community, I'd love to hear from you.
This podcast is produced by the Icons of Real Estate - #1 Real Estate Podcast Network. If you are a real estate professional, apply to be a guest speaker across the network.